Open post
Four hands hold up eco-friendly items: a paper bag, a round container, stackable food trays, and a disposable coffee cup against a green and light background—an inspiring scene for anyone learning how to choose the right food packaging boxes.

How to Choose the Right Food Packaging Boxes

Food businesses in Singapore live and die by small operational details, and packaging boxes sit right at the centre of that. A box that leaks gravy on a delivery bag, or one that lets fried food go soggy before it reaches the customer, undoes hours of work in the kitchen within minutes. Picking the right food packaging box is less about finding a single perfect container and more about understanding what a specific dish needs and matching a box design to that need consistently, order after order. The pressure only grows as delivery platforms and takeaway culture push more meals out of the kitchen and into bags, bikes, and lift lobbies before anyone takes the first bite.

Understand That Different Foods Need Different Boxes

A box built for cold items like salads or desserts behaves very differently from one meant to hold a hot stir-fry or soup straight off the wok. Hot food generates steam, and a box without proper ventilation traps that moisture and turns crispy items limp within the time it takes to travel across town. Cold or dry food, on the other hand, benefits more from a tight seal that keeps out air and prevents spillage during transport. Trying to use one box style across an entire menu often means some dishes arrive looking far worse than they left the kitchen.

Food-Grade Material Is Non-Negotiable

Any box coming into direct contact with food needs to be made from material rated safe for that purpose, which rules out repurposing general-use containers no matter how convenient they seem. Food-grade plastics are manufactured and tested to avoid leaching chemicals or odours into what they hold, which matters enormously for anything served hot or containing oils and sauces. Cutting corners here is a false economy, since the cost difference between food-grade and non-food-grade packaging is usually small compared to the risk of a customer complaint or a spoiled batch of food. Reputable suppliers will always be clear about which of their boxes are certified for food contact.

Leak Resistance and Heat Tolerance for Hot Dishes

Gravies, curries, and soups are some of the hardest items to package well, since they combine heat, moisture, and a tendency to shift around during transport. A box with a secure, well-fitted lid prevents spillage even when a delivery rider takes a corner too fast, while heat-tolerant material avoids warping or softening under a hot dish fresh off the stove. Compartmentalised boxes solve a related problem for caterers plating multiple items in one container, keeping sauces separate from rice or noodles so nothing turns soggy before the meal is served. These details matter most for stalls and caterers doing high delivery volumes, where a single bad packaging choice repeated across hundreds of orders becomes a real cost.

Sizing Boxes to Match Actual Portions

An oversized box makes a portion look smaller than it is and wastes money on unnecessary material, while an undersized box risks spillage and a messy presentation when the lid barely closes. Matching box size to standard portion sizes across a menu keeps both cost and presentation consistent, which matters for repeat customers who notice when portions or packaging feel inconsistent between orders. Businesses running a tight menu with a handful of standard dish sizes often do better sourcing a small, well-chosen range of box sizes rather than a huge assortment that adds complexity to inventory without much benefit.

Stackability Matters for Delivery and Storage Alike

Boxes that stack cleanly protect food during transport and make life easier in a busy kitchen where counter space is limited during peak hours. A poorly designed box that wobbles or crushes under the weight of another box on top of it risks ruining an order before it even leaves the kitchen. This becomes especially important for caterers packing large batch orders, where dozens of boxes need to travel together safely, which is where sourcing purpose-built catering and ready-to-eat packaging designed with stacking and transport in mind saves a lot of trouble compared to using generic containers.

Thinking Ahead to How Customers Will Reheat or Store Leftovers

A good number of boxed meals do not get eaten immediately, especially with office lunches ordered ahead or family dinners picked up early and reheated later in the evening. Boxes that can go straight into a microwave without warping save the customer an extra step of transferring food to another container, which is a small convenience that builds loyalty over repeat orders. Boxes that seal well also double as short-term storage in a fridge, letting customers keep leftovers without needing to find their own container. Thinking about this second life for a food box, beyond the initial delivery or takeaway moment, is a detail that separates thoughtful packaging choices from purely functional ones.

Weighing Cost Against Presentation

Every food business balances margin against presentation, and packaging sits right at that intersection. A box that looks premium but eats too much into margin is not sustainable at scale, while a box so cheap it undermines the food’s presentation can quietly cost a business repeat customers. The right balance usually comes from matching packaging quality to the price point of the food itself, so a mid-range meal gets a clean, functional box while a premium dish gets packaging that matches the price customers are paying for it.

Choosing the right food packaging box comes down to knowing the dish, respecting food safety requirements, and being honest about how the box will actually be handled between the kitchen and the customer’s table. Businesses that treat packaging as an afterthought tend to discover its importance only after complaints start coming in about leaks or soggy food. Getting it right from the start, with material, size, and design chosen deliberately for each type of dish, protects both the food and the reputation built around it.
Open post
A person in protective clothing and gloves examines samples stored in a refrigerated unit under blue lighting, highlighting the importance of Refrigerator Repair Singapore for professional cooling system repairs.

Refrigerator Repair Singapore for Professional Cooling System Repairs

Refrigerator repair in Singapore requires a different approach than appliance repair in many other countries. The combination of Singapore’s tropical climate, the high density of residential and commercial premises, and the reliance on refrigeration for food safety in a country without seasonal cold periods means that refrigerator failures are treated with appropriate urgency. When a refrigerator stops cooling in Singapore, the clock on food safety starts immediately.

Why Singapore’s Climate Creates Specific Repair Urgency

In temperate climates, a household refrigerator failure allows some hours of grace: the ambient temperature is cool enough that refrigerated food remains safe for a period even without active cooling. In Singapore’s ambient temperature of 27 to 33 degrees Celsius, food that was properly refrigerated begins to warm toward the unsafe zone (above 4 degrees Celsius) within a few hours of cooling failure.

This urgency is not hypothetical. Singapore’s Food Agency defines food safety temperature requirements precisely: perishable food must be kept at 4 degrees Celsius or below, or at 60 degrees Celsius or above. Food that has been in the temperature danger zone for more than four hours should be discarded. A refrigerator failure discovered in the morning means that decisions about the previous evening’s grocery delivery may already be complicated.

Professional refrigerator repair in Singapore that responds promptly and resolves the fault effectively minimises the food loss, the food safety risk, and the household disruption associated with refrigerator failure.

What Professional Refrigerator Repair Covers

Professional refrigerator repair in Singapore addresses the full range of cooling system faults and related issues that affect refrigerator performance.

  • Refrigerant leaks and recharging: A refrigerator losing refrigerant through a small leak loses cooling capacity gradually. Locating the leak, repairing it, and recharging the system with the correct refrigerant to the correct pressure restores cooling. In Singapore, only certified technicians holding the appropriate Singapore Environment Council certification are legally permitted to handle refrigerants.
  • Compressor diagnosis and replacement: Compressor failure is the most expensive single refrigerator repair. A professional diagnosis confirms whether the compressor has failed or whether the loss of cooling is attributable to a less expensive fault such as a start relay or capacitor, which are associated components that can cause the same symptom at a fraction of the replacement cost.

Evaporator and condenser coil service: Blocked or iced-over evaporator coils and dirty condenser coils both impair cooling efficiency. Cleaning and, where necessary, replacing these components restores efficiency.

Electronic control board repair: Modern refrigerators use electronic control boards to manage the compressor, fans, and defrost system. Control board failures can cause a range of symptoms from complete cooling failure to intermittent temperature inconsistency.

Selecting a Professional Repair Service

Refrigerator repair in Singapore from a professional service requires several qualities that distinguish reliable service from inadequate alternatives.

  • Genuine refrigerant handling complianced: Any repair involving refrigerant must be performed by a technician with the appropriate certification. Ask for confirmation of this certification for any repair involving refrigerant recovery or recharge.
  • Parts quality: A compressor replacement or evaporator replacement using a genuine or OEM-equivalent part will outlast one using a low-quality substitute. Ask about the provenance of major replacement parts.
  • Diagnostic fee transparency: A professional service charges a diagnostic fee for the time and expertise required to diagnose the fault correctly. Be wary of services that quote repair costs before diagnosing, or that offer “free” diagnosis in lieu of a transparent repair quote.
  • Warranty on repair: A repair service confident in the quality of their diagnosis and workmanship provides a warranty on parts and labour. The duration and conditions of this warranty is a useful indicator of the service’s confidence in their own work.

As Singapore’s Consumers Association notes in its guidance on appliance repair, “Consumers should ask for a written quote specifying the fault diagnosis, the parts to be replaced, and the labour costs before authorising any repair work.” This protects both the consumer and the repair provider.

When to Repair vs. Replace

Professional cooling system repair in Singapore makes economic sense when the repair cost is proportionate to the appliance’s age, condition, and remaining service life. A refrigerator that is three years old and requires a 300-dollar thermostat replacement is worth repairing. A 12-year-old refrigerator requiring a compressor replacement is a more nuanced decision that the repair technician’s honest assessment of the appliance’s overall condition should inform. Professional refrigerator repair in Singapore from a service that provides honest, informed guidance on the repair-versus-replace decision is the most useful resource when your cooling system needs attention.

Open post
A person sits at a table looking stressed while holding a document, with a jar of coins and a small wooden house model in the foreground—highlighting the struggles of seeking a personal loan for low income Singapore residents.

Personal Loan for Low Income Singapore: Accessible Options That Work

The quest for a personal loan for low income singapore earners reflects a fundamental truth about modern financial systems: access to credit remains stratified by economic class, yet necessity knows no income bracket. Throughout history, societies have grappled with the challenge of providing financial assistance to those who need it most whilst protecting them from exploitation. Singapore’s approach to this age-old dilemma combines strict regulation with pragmatic accommodation, creating pathways for lower-income individuals to access credit when circumstances demand it. Understanding these pathways requires examining both the mechanisms available and the historical context that shaped them.

The Landscape of Low-Income Lending

Singapore’s definition of low income varies by context, but for practical lending purposes, individuals earning below £2,500 monthly typically face additional scrutiny and limitations. The system recognises that those earning modest wages deserve financial access whilst acknowledging the heightened risk such lending entails. This balance between accessibility and protection shapes every aspect of how a personal loan for low income singapore workers operates.

Banks traditionally serve middle and upper-income borrowers, setting minimum income requirements that often begin at £30,000 annually. This threshold, whilst rational from a risk management perspective, effectively excludes a significant portion of the working population. Licensed money lenders, regulated under the Moneylenders Act, fill this gap. They accept borrowers earning as little as £1,500 monthly, provided they meet other criteria.

A person sits at a table looking stressed while holding a document, with a jar of coins and a small wooden house model in the foreground—highlighting the struggles of seeking a personal loan for low income Singapore residents.

Government Assistance Programmes

Before pursuing commercial loans, lower-income Singaporeans should explore government assistance schemes designed specifically for their circumstances:

  • The Ministry of Social and Family Development offers Short-to-Medium Term Assistance for urgent financial needs 
  • ComCare provides various forms of financial support for lower-income households 
  • The Community Development Councils offer localised assistance programmes 
  • Self-Help Groups provide interest-free loans to members of specific communities

These programmes exist precisely because policymakers recognised that commercial lending alone cannot adequately serve those at the economic margins. The personal loan for low income singapore residents through these channels often comes with more favourable terms than any commercial alternative.

Licensed Money Lenders: The Primary Commercial Option

For those who do not qualify for government assistance or require amounts exceeding what such programmes provide, licensed money lenders represent the most accessible option. The regulatory framework governing these institutions contains specific provisions for lower-income borrowers:

  • Borrowers earning less than £20,000 annually may borrow up to £3,000 
  • Those earning between £20,000 and £40,000 annually may borrow up to six times their monthly income 
  • Interest rates are capped at 4% per month across all income levels 
  • Late fees cannot exceed £60 monthly regardless of loan size

These regulations reflect lessons learned from darker periods when unscrupulous lenders preyed upon the financially vulnerable. The protections now in place represent decades of policy evolution aimed at balancing access with safety.

What Lenders Examine

When assessing applications for a personal loan for low income singapore applicants, licensed lenders consider multiple factors beyond mere salary:

  • Employment stability and tenure with current employer 
  • Existing debt obligations and repayment history 
  • Monthly expenses relative to income 
  • Presence of co-borrowers or guarantors 
  • Assets that might serve as collateral

A stable employment history often compensates for modest income. Someone earning £1,800 monthly who has worked at the same establishment for five years presents a more attractive proposition than someone earning £2,500 who changes jobs frequently. Lenders understand that financial reliability transcends income level.

The Role of Credit Bureaus

Singapore’s credit bureau system maintains records on every individual’s borrowing and repayment behaviour. This system serves lower-income borrowers well when they maintain good credit histories. A modest earner with consistent repayment records may access better terms than a higher earner with past defaults. The personal loan for low income singapore workers becomes more accessible when supported by demonstrated financial responsibility.

Alternative Credit Building Strategies

Lower-income individuals seeking to improve their borrowing prospects might consider:

  • Maintaining a basic savings account showing regular deposits 
  • Using secured credit cards to establish positive credit history 
  • Becoming an authorised user on a family member’s credit account 
  • Joining credit cooperative societies 
  • Participating in community savings circles

These strategies require patience but provide foundations for future financial access without the immediate costs associated with borrowing.

The Reality of Borrowing Costs

Honesty compels acknowledgment that a personal loan for low income singapore earners typically costs more than loans available to higher earners. This reflects risk assessment rather than malice. A borrower with limited financial cushion faces greater difficulty managing unexpected expenses, increasing default probability. Lenders price this risk into their interest rates.

However, the regulatory caps prevent this pricing from becoming predatory. The maximum monthly interest of 4% applies uniformly, and additional fees face strict limitations. These protections distinguish Singapore’s regulated lending environment from the usurious practices that historically plagued similar markets elsewhere.

Making Informed Decisions

Before pursuing any loan, lower-income borrowers should:

  • Calculate exact monthly repayment amounts and ensure they fit comfortably within their budget 
  • Understand all fees and charges comprehensively 
  • Verify the lender’s licence through the Registry of Moneylenders 
  • Consider whether the expense necessitating the loan might be deferred or reduced 
  • Explore all government assistance options first

The wisdom of borrowing lies not in the availability of credit but in the careful assessment of whether that credit serves one’s long-term interests.

Conclusion

The architecture of Singapore’s lending system acknowledges that financial need exists across all income levels whilst implementing safeguards against exploitation. Through government programmes, regulated private lenders, and transparent rules, the system provides pathways for those earning modest wages to access capital when truly necessary. Success in navigating this system requires understanding one’s options, maintaining financial discipline, and approaching borrowing with the seriousness it deserves. With proper knowledge and careful planning, securing a personal loan for low income singapore residents becomes a manageable process rather than an insurmountable challenge.

Open post

Legal Money Lender Singapore: Navigate Regulated Lending Safely

Distinguishing a legal money lender in Singapore from unlicensed operators represents a critical survival skill in the modern financial landscape, one that separates protected borrowers from vulnerable victims of exploitation. The regulatory ecosystem established by the Ministry of Law creates clear boundaries between legitimate lending and predatory practices, yet understanding these distinctions requires systematic examination of the governing framework.

The Regulatory Architecture

Singapore’s approach to moneylending demonstrates sophisticated understanding of balance between access and protection. The Moneylenders Act 2008 established comprehensive oversight, creating an environment where borrowers can access credit whilst maintaining robust safeguards against exploitation. This legislative structure evolved from earlier, less protective systems that permitted abusive practices.

The Registry of Moneylenders, operating under Ministry of Law authority, maintains definitive records of all licensed operators. This centralised verification system provides borrowers with unambiguous means to confirm legitimacy before engaging any lending service. As official guidelines specify, the Registry “cultivates a safe and professional moneylending industry in Singapore” through rigorous oversight and enforcement.

Distinguishing Legitimate Operators

Licensed moneylenders Singapore must satisfy strict criteria that separate them from illegal loan sharks:

Mandatory Licensing Requirements: 

  • Valid licence issued by the Registrar of Moneylenders 
  • Licence number prominently displayed at business premises 
  • Annual renewal ensuring ongoing compliance 
  • Public verification through Ministry of Law website

Operational Standards: 

  • Physical business address registered with authorities 
  • Written loan contracts in comprehensible language 
  • Transparent fee structures disclosed upfront 
  • Prohibition against SMS or unsolicited advertising

Interest Rate Regulations: 

  • Maximum 4 per cent monthly interest 
  • Late interest capped at identical 4 per cent monthly 
  • Administrative fees limited to 10 per cent of principal 
  • Late payment fees capped at sixty dollars monthly

The Act specifies that “the maximum interest rate moneylenders can charge is 4% per month,” applying uniformly across all borrower categories.

Borrowing Limits and Protections

The regulatory framework establishes graduated borrowing limits correlated with income levels, preventing over-indebtedness:

  • Annual income below S$20,000: Maximum S$3,000 across all licensed lenders 
  • Annual income above S$20,000: Up to 6 times monthly income 
  • Foreigners with income below S$10,000: Maximum S$500 
  • Foreigners earning S$10,000 to S$20,000: Maximum S$3,000

These restrictions reflect understanding that borrowing capacity must align with repayment ability. The limits apply cumulatively across all licensed moneylenders, preventing borrowers from accumulating unsustainable debt by approaching multiple lenders.

Additional protections include mandatory disclosure requirements. Licensed operators must explain all terms completely before loan execution. Borrowers receive written contracts detailing principal amounts, interest rates, repayment schedules, and all applicable fees. This transparency contrasts sharply with illegal lending, where terms remain deliberately opaque.

The Verification Imperative

Before engaging any moneylender, borrowers must verify licensing status through the Ministry of Law’s official registry. This step takes minutes but prevents potentially catastrophic consequences. The registry provides searchable records including business names, licence numbers, addresses, and contact information.

Warning signs indicating unlicensed operations include:

  • Unsolicited loan offers via SMS or messaging platforms 
  • Requests for upfront fees before approval 
  • Absence from official Ministry of Law listings 
  • Inability to provide licence number 
  • Pressure tactics or aggressive communication 
  • Promises of instant approval without documentation

Licensed money lender operate transparently within regulatory bounds. Illegal lenders exploit desperation, creating debt traps through deception and intimidation.


Recent Regulatory Developments

The 2025 amendments to Singapore’s moneylending framework introduced enhanced protections. Recent reforms address data sharing, self-exclusion mechanisms, and stricter licensing standards. As regulatory updates note, “amendments to the Moneylenders Act of Singapore introduce new laws regarding the lending limits, licensing regulations, and safeguarding against predatory lending practices.”

These reforms enable borrowers to access their credit information through the Moneylenders Credit Bureau, promoting informed decision-making. The Self-Exclusion Listing allows individuals struggling with debt to voluntarily prevent themselves from obtaining additional loans from licensed lenders, providing protection during financial difficulty.

Rights and Recourse

Borrowers dealing with licensed moneylenders enjoy specific protections under law:

  • Right to transparent information about all charges 
  • Protection against harassment or threatening behaviour 
  • Clear repayment schedules without hidden conditions 
  • Legal recourse through Ministry of Law complaints process 
  • Prohibition against solicitation without borrower initiation

Licensed operators face substantial penalties for violations, including licence revocation, fines, and potential criminal charges. This enforcement structure maintains industry standards and protects borrowers from unethical practices.

Alternative Considerations

Before approaching any moneylender, borrowers should evaluate alternatives:

  • Bank personal loans offering lower interest rates 
  • Government assistance schemes for qualifying individuals 
  • Credit counselling services for debt management 
  • Negotiating payment arrangements with existing creditors 
  • Seeking support from community organisations

These options may provide more sustainable solutions, particularly for non-emergency situations or longer-term financial needs.

The Risk Landscape

Engaging unlicensed lenders exposes borrowers to severe consequences. Illegal operators, commonly termed loan sharks or Ah Longs, employ intimidation, harassment, and violence to enforce repayment. They charge exorbitant interest rates unconstrained by regulation. They operate outside legal frameworks, providing borrowers no recourse or protection.

The Ministry of Law maintains the X-Ah Long hotline at 1800-924 5664 for reporting suspected illegal lending. Such reports contribute to enforcement efforts that protect the broader community.

Strategic Borrowing Principles

When circumstances necessitate borrowing from moneylenders, several principles guide responsible engagement:

  • Verify licensing status before any commitment 
  • Understand complete cost structure including all fees 
  • Assess realistic repayment capacity before proceeding 
  • Read all documentation thoroughly before signing 
  • Maintain records of all transactions and communications 
  • Report any suspicious or unethical behaviour immediately

These practices transform borrowing from reactive desperation into measured financial strategy.

Understanding these mechanisms empowers individuals to navigate Singapore’s lending landscape safely, distinguishing legitimate operators from predators. When genuine need meets proper verification, engaging a legal money lender in singapore becomes a protected transaction rather than a dangerous gamble.

Open post
plastic food container

Revolutionary Changes in Modern Food Container Technology

When you select a plastic food container for tomorrow’s lunch, you’re making a choice that connects you to a global industry worth billions of pounds and an environmental challenge that grows more complex each year. This seemingly mundane decision reflects broader tensions between convenience, sustainability, and health consciousness that define contemporary consumer culture in ways that would have been unimaginable just decades ago.

The Hidden Chemistry of Food Preservation

Modern food storage containers represent sophisticated engineering achievements disguised as everyday objects. The molecular architecture of these vessels involves carefully calibrated polymer chains designed to create optimal barrier properties whilst maintaining structural integrity across temperature variations and repeated use cycles.

Consider the intricate balance required: containers must prevent moisture loss without trapping excess humidity, allow some gas exchange whilst blocking contamination, and maintain chemical stability across diverse food types and storage conditions. This balancing act requires precise understanding of polymer science, food chemistry, and consumer behaviour patterns.

The manufacturing process itself reveals fascinating complexities. Injection moulding techniques must account for thermal expansion, cooling rates, and stress distribution to produce containers that won’t crack under normal use. Quality control measures involve testing for everything from impact resistance to chemical migration rates under accelerated aging conditions.

Global Supply Chains and Local Regulations

The journey of food storage containers from production facilities to kitchen cupboards traverses complex international supply networks that reflect globalisation’s reach into the most intimate aspects of daily life. Raw materials sourced from multiple continents undergo processing in specialised facilities before assembly, packaging, and distribution through retail channels spanning the globe.

Singapore’s approach to regulating imported food contact materials demonstrates how small nations can exert significant influence over global manufacturing standards. The city-state’s Health Sciences Authority maintains rigorous testing protocols that often exceed requirements in larger markets, effectively forcing international manufacturers to meet higher safety standards across their entire production lines.

Consumer Behaviour and Storage Patterns

Research into how people actually use food storage containers reveals surprising gaps between manufacturer intentions and real-world applications. Studies indicate that most consumers significantly underestimate the importance of proper container selection for different food types, leading to suboptimal preservation results and potential safety concerns.

Temperature abuse represents one of the most common misuse patterns. Despite clear labelling, many users regularly subject containers to thermal conditions beyond their design parameters, whether through microwave use, dishwasher cycles, or storage near heat sources. This behaviour accelerates chemical migration whilst compromising structural integrity.

Food acidity presents another frequently misunderstood factor. Tomato-based sauces, citrus products, and vinegar-containing foods can dramatically increase the rate at which plastic additives migrate into stored food, yet most consumers remain unaware of these interactions.

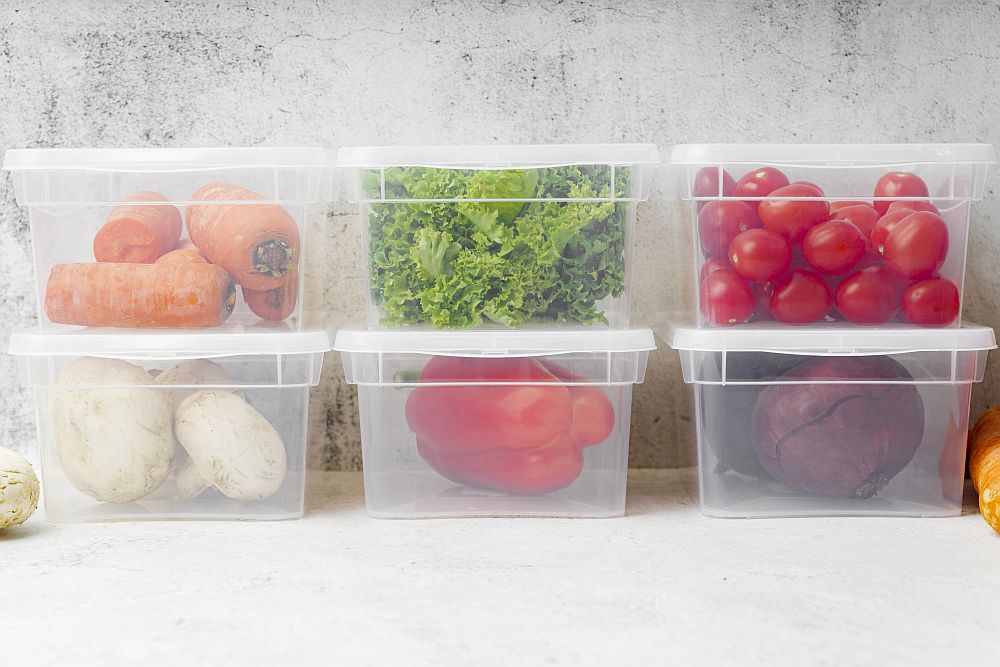
Six plastic food containers filled with carrots, lettuce, cherry tomatoes, mushrooms, a red bell pepper, and a red onion are neatly arranged on a white surface against a light background.

Innovative Materials and Future Technologies

The next generation of food storage solutions promises to address many current limitations through advanced materials science and innovative design approaches. Bio based polymers derived from plant materials offer potential alternatives to petroleum based plastics whilst maintaining necessary performance characteristics.

Smart packaging technologies integrate sensors that can monitor food freshness, storage conditions, and container integrity in real time. These developments represent convergence between traditional packaging science and emerging digital technologies that could transform how we understand food safety and waste reduction.

  • Advanced barrier coatings that provide superior protection with thinner walls 

  • Temperature-sensitive indicators that alert users to thermal abuse 

  • Antimicrobial additives that extend food safety margins 

  • Biodegradable options that maintain performance whilst reducing environmental impact 

  • Modular designs that optimise storage efficiency and reduce waste

Economic Implications of Storage Choices

The economics of food storage extend far beyond initial purchase prices. Proper container selection can significantly impact food waste rates, which represent substantial hidden costs for most households. Research suggests that optimal storage conditions can extend food freshness by thirty to fifty percent for many products, translating into meaningful financial savings over time.

Professional food service operations have long recognised these economic relationships, investing in specialised storage systems that maximise product life whilst minimising contamination risks. Home consumers increasingly adopt similar approaches as awareness of food waste costs grows alongside environmental consciousness.

Regional Variations in Usage Patterns

Cultural differences significantly influence food storage preferences and practices across different regions. Asian markets tend to favour smaller, portion specific containers that align with frequent shopping patterns and smaller refrigeration units. European consumers often prioritise durability and multifunctionality, while American preferences lean toward larger capacity options suitable for bulk purchasing habits.

These variations drive different product development priorities and regulatory approaches across global markets. Understanding these patterns helps explain why certain container types succeed in specific regions whilst failing elsewhere, despite seemingly superior technical specifications.

Making Informed Storage Decisions

Navigating the complexities of modern food storage requires understanding both technical specifications and practical usage patterns. Container selection should account for intended food types, storage duration, temperature conditions, and disposal considerations to optimise both safety and environmental impact.

Regular replacement schedules prevent accumulated wear from compromising container performance, whilst proper cleaning techniques extend useful life without introducing contamination risks. The intersection of these factors determines the overall value proposition of different storage solutions.

As we continue to balance convenience, safety, and environmental responsibility, the humble plastic food container serves as a microcosm of larger societal challenges that require thoughtful consideration rather than reflexive responses. The future lies in making increasingly informed choices about this essential plastic food container.

Open post
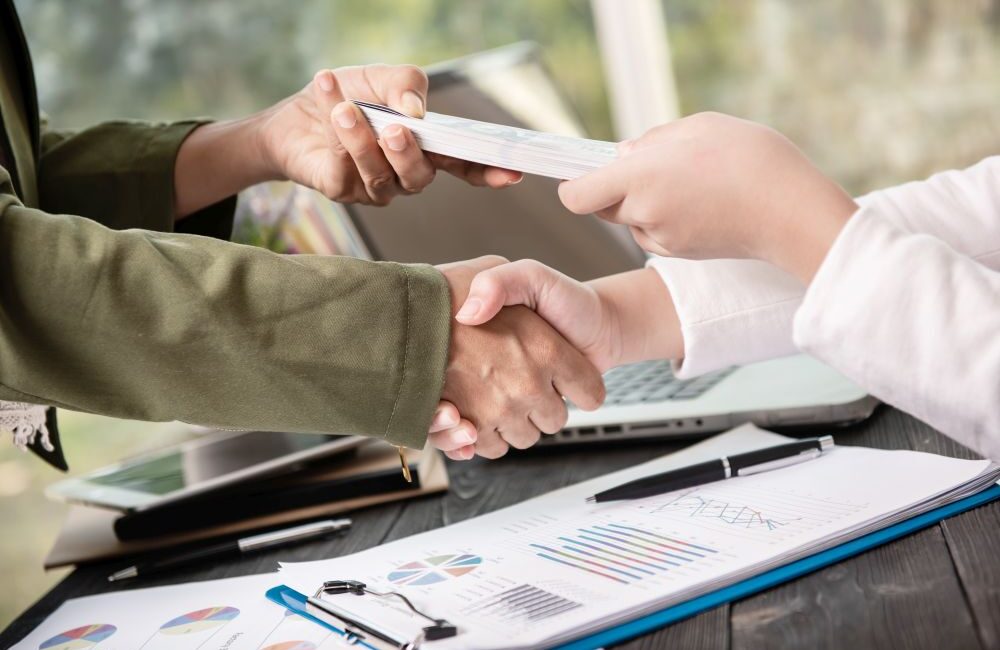
Two people shaking hands while exchanging a stack of cash, with business documents and a laptop on the table—illustrating a transparent transaction with a legal money lender in Singapore.

Singapore’s Financial Lifeline: Your Complete Moneylender Guide

In the intricate tapestry of Singapore’s financial landscape, a moneylender serves as more than merely a lending institution; they represent a crucial bridge between immediate financial needs and long-term economic stability. Like the careful physician who must understand both the symptoms and the underlying condition, navigating Singapore’s moneylending sector requires a nuanced appreciation of its regulatory framework, consumer protections, and the delicate balance between accessibility and responsibility.

The story of moneylending in Singapore is one of evolution and refinement, much like the progression of medical understanding from crude remedies to precision medicine. What began as an unregulated marketplace has transformed into a sophisticated system where borrower protection stands paramount.

The Architecture of Legal Lending

Singapore’s approach to regulating money lenders reflects a profound understanding of human financial behaviour. The Moneylenders Act 2008, much like a well-crafted therapeutic protocol, establishes clear boundaries while maintaining flexibility for legitimate financial needs.

Under Singapore law, any person who lends money in consideration of a larger sum being repaid must hold a requisite moneylender’s licence, unless exempted or excluded. This fundamental principle creates a protective framework that distinguishes legitimate lending from predatory practices.

The regulatory landscape recognises three distinct categories of lenders:

•      Licensed moneylenders: Entities holding official licences from the Registrar of Moneylenders

•      Exempt moneylenders: Institutions specifically exempted under special circumstances

•      Excluded moneylenders: Organisations regulated under other financial laws, such as banks and finance companies

The 2025 Regulatory Renaissance

The 2025 New Licensed Moneylender Act introduces significant updates, emphasising enhanced consumer protection and modernised standards for lenders. These amendments represent more than mere regulatory adjustments; they constitute a fundamental reimagining of the borrower-lender relationship.

The new framework introduces stricter licensing requirements, enhanced transparency mandates, and fortified enforcement mechanisms. Interest rates remain capped at 4% per month, with administrative fees limited to 10% of the loan principal, creating predictable cost structures for borrowers.

Key protective measures include:

•      Borrowing limits adjusted based on income levels and credit history

•      Mandatory disclosure of all loan terms and conditions

•      Prohibition of predatory practices such as harassment or withholding personal documents

•      Self-exclusion programmes allowing individuals to voluntarily restrict their borrowing capacity

The Economics of Borrowing: Understanding True Costs

The financial mathematics of moneylending in Singapore follows stringent parameters designed to prevent exploitation. Since October 2015, the maximum interest rate has been capped at 4% per month, applying universally regardless of income level or loan security status.

This regulatory ceiling extends to late payments, where the highest rate of late interest remains at 4% per month, calculated only on the overdue amount rather than the entire outstanding balance. Such precision in calculation prevents the exponential debt growth that often characterises predatory lending.

Additional fees remain strictly regulated:

•      Administrative fee: Maximum 10% of principal, deducted at disbursement

•      Late payment fee: Capped at S$60 per month

•      Legal costs: Only recoverable through court orders

Perhaps most significantly, total charges cannot exceed the original principal amount, creating an absolute ceiling on borrowing costs that prevents debt spirals.

Income-Based Borrowing Thresholds

Singapore’s approach to lending limits reflects a sophisticated understanding of financial capacity. Borrowing limits vary based on annual income, with unsecured loans capped at specific multiples of monthly earnings. These calculations consider total outstanding amounts across all licensed money lenders, preventing individuals from accumulating unsustainable debt burdens.

For secured loans, borrowing capacity expands considerably, recognising the reduced risk profile when collateral backs the arrangement. This tiered approach acknowledges different financial circumstances while maintaining protective boundaries.

Consumer Protection: Beyond Mere Regulation

The true strength of Singapore’s moneylending framework lies not merely in its rules but in their enforcement. The Ministry of Law maintains comprehensive oversight, with dedicated hotlines (1800-2255-529) for reporting violations and a formal feedback system for consumer complaints.

Licensed money lenders face strict operational requirements:

•      Physical presence: Must conduct face-to-face verifications at registered offices

•      Advertising restrictions: Cannot solicit loans through SMS or unsolicited communications

•      Documentation requirements: Must explain terms in languages borrowers understand

•      Harassment prohibition: Criminal penalties apply to threats or abusive behaviour

The Digital Deception: Recognising Legitimate Lenders

In our increasingly connected world, distinguishing legitimate money lenders from fraudulent operators requires vigilance. Licensed lenders must have physical offices and cannot approve loans entirely online or through messaging applications. This requirement serves as a crucial filter against digital scams.

Legitimate advertising channels remain limited to business directories, official websites, and premises-based displays. Any loan offers received through unsolicited SMS, email, or phone calls likely originate from unlicensed operators.

The Path Forward: Responsible Borrowing

Understanding Singapore’s moneylending regulations empowers borrowers to make informed decisions. The regulatory framework creates space for legitimate financial needs while providing robust protection against exploitation. Like any powerful tool, borrowing requires careful consideration of purpose, capacity, and consequences.

The sophisticated balance achieved in Singapore’s approach, protecting consumers while maintaining market functionality, serves as a model for responsible financial regulation. For those navigating financial challenges, this framework ensures access to credit remains available through a properly regulated, legal money lender in Singapore.


Open post

Your Complete Guide to Safe and Smart Borrowing in Singapore (2024)

In today’s fast-paced Singapore economy, there are times when you might need quick access to funds. Whether it’s for emergency medical expenses, business opportunities, or debt consolidation, finding a reliable legal loan Singapore option is crucial. As a financial advisor with over 15 years of experience, I’ve guided countless clients through the borrowing process, and I’m here to share what you need to know.

Why Consider Licensed Moneylenders?

Let me be frank – banks aren’t always the answer. According to recent data from the Ministry of Law, approximately 150,000 Singaporeans turn to licensed moneylenders annually. Why? Because they offer faster processing, more flexible terms, and often accept borrowers whom banks might reject.

Understanding Your Borrowing Limits

Now, pay attention to this bit – it’s vital. The maximum amount you can borrow depends on your annual income:

– For Singaporeans and PRs earning less than $20,000: Up to $3,000

– For those earning $20,000 or more: Up to 6 times monthly income

– For foreigners earning less than $10,000: Up to $500

– For foreigners earning $10,000-$20,000: Up to $3,000

Expert Tip: Always calculate your debt-to-income ratio before borrowing. Keep it below 40% to maintain financial health.

The Application Process: What You’ll Need

My dear reader, getting a loan isn’t as complicated as you might think. You’ll need:

– Your NRIC or passport

– Proof of residence

– Recent payslips

– CPF contribution history

– Bank statements from the past 3 months

Interest Rates and Fees: The Truth

Here’s something that might surprise you – licensed moneylenders in Singapore are strictly regulated. The maximum interest rate they can charge is 4% per month. Administrative fees are capped at 10% of the principal amount.

Warning Signs of Illegal Lenders

I’ve seen too many people fall victim to loan sharks. Here’s what legitimate lenders will never do:

– Advertise through WhatsApp or SMS

– Ask for your SingPass credentials

– Demand upfront fees

– Threaten or harass you

Smart Borrowing Strategies

In my years of advising clients, I’ve developed these golden rules:

  1. Borrow only what you need and can repay
  2. Compare at least three different lenders
  3. Read the contract thoroughly
  4. Keep all documentation
  5. Never miss a payment

Expert Tip: Create a dedicated repayment fund by setting aside 20% more than your monthly instalment. This provides a buffer for unexpected expenses.

The Impact on Your Credit Score

Listen carefully – your borrowing behaviour affects your credit score. The Credit Bureau Singapore (CBS) reports that 85% of Singaporeans maintain a good credit score. Join them by making timely repayments and managing your debt responsibly.

Alternative Options to Consider

Before rushing to borrow, consider these alternatives:

– Negotiating payment plans with existing creditors

– Tapping into your emergency savings

– Exploring government assistance schemes

– Consulting credit counselling services

Making Your Decision

My dear friend, borrowing money is a serious decision. According to the Ministry of Law’s 2023 report, 97% of borrowers from licensed moneylenders successfully repaid their loans. This shows that with proper planning and responsible borrowing, you can navigate financial challenges effectively.

Remember, seeking financial help isn’t shameful – it’s often a smart business decision when done right. Whether you’re dealing with unexpected expenses or seizing an investment opportunity, the key is to work with reputable legal moneylender Singapore institutions. If you’re considering taking a loan, I strongly recommend consulting with a legal money lender in Singapore who can provide personalised advice based on your specific situation.

Open post

Common Challenges and Solutions for Securing a Foreigner Loan in Singapore

Who would have thought that a desperate attempt to fund my durian addiction would lead me to become an expert on foreigner loans in Singapore? Certainly not me! Hi, I’m Jake Thompson, and my journey from wide-eyed expat to savvy borrower started with a craving and an empty wallet.

Picture this: It’s my first month in Singapore, and I’ve just discovered the king of fruits. I’m hooked, but my bank account is as empty as a void deck at 3 AM. In my desperation for durian money, I stumbled into the world of foreigner loans Singapore-style. Fast forward two years, and I’m now helping fellow expats navigate this financial maze, armed with hard-earned wisdom and a slightly concerning knowledge of exotic fruit financing.

So, let’s dive into the challenges and solutions of securing a foreigner loan in Singapore, shall we?

Challenge 1: The “You’re Not From Around Here” Hurdle

The Reality: Limited Options, Not No Options

Many foreigners think getting a loan in Singapore is as impossible as finding peace and quiet during hungry ghost month. The truth? It’s challenging, but not impossible.

Solution:

– Research lenders specializing in foreigner loans, like JD Credit

– Prepare extensive documentation proving your stability and income

– Consider a local guarantor if possible

Remember, it’s not about being local; it’s about proving you’re a safe bet!

Challenge 2: The Salary Showdown

The Truth: Size (of your paycheck) Matters

In Singapore, your salary often determines your loan eligibility. As a foreigner, you might face higher income requirements.

Solution:

– Seek employment with a reputable company

– Consider additional income sources (e.g., freelance work)

– Be realistic about loan amounts based on your income

Pro tip: At JD Credit, they understand the unique financial situations of expats and offer tailored solutions.

Challenge 3: The Visa Vexation

The Facts: Your Visa Type Can Make or Break Your Loan Application

Your visa status significantly impacts your eligibility for a foreigner loan Singapore. Work permits, employment passes, and permanent residency all carry different weights.

Solution:

– Understand how your visa type affects loan eligibility

– Consider applying for a loan after securing a more stable visa status

– Be transparent about your visa situation with potential lenders

JD Credit offers guidance on loan options based on various visa types, making the process less daunting.


Challenge 4: The Credit Score Conundrum

Reality Check: Your Home Country’s Credit Score Doesn’t Follow You

Many expats are shocked to learn their stellar credit score back home means zilch in Singapore.

Solution:

– Start building a local credit history ASAP

– Consider secured credit cards or small loans to establish credit

– Maintain a good relationship with your bank

Remember, in Singapore, you’re essentially starting your credit journey from scratch!

Challenge 5: The Collateral Quandary

The Truth: No Local Assets Can Limit Your Options

Without local property or assets, securing a foreigner loan can be tricky.

Solution:

– Explore unsecured loan options

– Consider using movable assets as collateral (e.g., vehicles)

– Look into joint loan options with a local co-borrower

JD Credit offers various loan types for foreigners, understanding that not everyone has a condo in Orchard to use as collateral.

The Singapore Special: Navigating Our Unique Financial Landscape

Borrowing as a foreigner in Singapore comes with its own set of quirks:

  1. Strict Regulations: Singapore’s tight financial rules can make qualifying challenging but also protect you from predatory lending.
  2. Cultural Nuances: Understanding local financial etiquette can smooth your loan journey.
  3. The Importance of “Face”: Building relationships with lenders can be as crucial as your paperwork.


At JD Credit, they’re experts in helping foreigners navigate these Singapore-specific factors to find the best loan solution.

Tips from an Expat Who’s Been There, Borrowed That

After my journey from durian-crazed newbie to loan-savvy expat, here are my top tips:

  1. Do Your Homework: Understand the local lending landscape before applying.
  2. Be Realistic: Don’t expect the same loan terms as in your home country.
  3. Build Local Connections: A good network can lead to better loan options.
  4. Plan for the Future: Consider how long you’ll be in Singapore and borrow accordingly.
  5. Seek Expert Advice: Companies like JD Credit can be invaluable resources.

Wrapping Up: Your Singaporean Financial Journey Starts Here

As I reflect on my transformation from clueless expat to foreigner loan aficionado, I’m reminded of why I love sharing my experience. Every fellow expat who successfully navigates a loan is a victory – a step towards making Singapore feel more like home.

So, the next time you’re considering a foreigner loan in Singapore, remember – it’s challenging but not impossible. Armed with the right information and a trusted partner like JD Credit, you can secure the funds you need, whether it’s for a business venture, education, or yes, even a durian feast.

And if you ever find yourself tempted by the siren call of Mao Shan Wang, remember my story. Sometimes, the best loan is the one that funds your passions – just maybe pace yourself on the durian, okay?

Is Singapore Frozen Elsa Theme Cake Worth It?

Is a Frozen Elsa theme cake worth it? This is a question many parents and party planners ask when considering how to make a celebration truly magical.

With the popularity of Disney’s Frozen and the enduring charm of Elsa, these cakes have become a favorite for birthdays and special events. Let’s explore whether investing in a frozen elsa theme cake is the right choice for your next party.

What Makes a Frozen Elsa Theme Cake Special

The Magic of Elsa and Frozen

Elsa is a beloved character whose story of courage and self-discovery resonates with children and adults alike. The Frozen movies have inspired countless themed parties, with Elsa cakes often taking center stage.

A frozen elsa theme cake captures the enchantment of Arendelle, featuring icy blue colors, snowflakes, and sometimes even edible ice palaces. These cakes are designed to delight fans and create a sense of wonder at any gathering.

Popularity Among Kids and Families

Frozen-themed celebrations remain in high demand years after the movie’s release. Children are captivated by Elsa’s magical powers, and parents appreciate the cake’s ability to bring the movie to life at home.

A frozen elsa cake is more than dessert—it’s a shared experience that brings families together and makes the guest of honor feel truly special.

Reasons to Choose a Frozen Elsa Theme Cake

Creating Unforgettable Memories

One of the biggest reasons to choose a frozen elsa theme cake from My Bake Studio is the joy it brings to the celebration. Children’s faces light up when they see their favorite character on a beautifully decorated cake.

The cake-cutting moment becomes a highlight of the event, and guests remember the occasion long after the last slice is served.

Unique Designs and Customization

Frozen elsa cakes come in a variety of designs, from simple single-tier cakes to elaborate multi-tiered masterpieces with intricate details. Bakers can customize the cake to match your vision, including colors, characters, and personal messages.

Whether you want Elsa standing atop an ice palace or a winter wonderland scene, the possibilities are endless. Customization ensures your cake is as unique as your celebration.

Is a Frozen Elsa Theme Cake Worth the Investment?

Value for Money

While a frozen elsa theme cake may cost more than a standard cake, the value it adds to your event can be significant. These cakes often become the centerpiece of the party, drawing attention and sparking conversation.

The price reflects not only the ingredients but also the artistry and time required to create such detailed designs. For many families, the joy and excitement the cake brings are well worth the investment.

Emotional Impact and Lasting Joy

The emotional value of a frozen elsa cake goes beyond its appearance. It helps create magical moments that children and guests cherish. The excitement of seeing Elsa in cake form can make a birthday or special event truly unforgettable.

Photos of the cake and celebration become keepsakes, preserving memories for years to come.

Comparing Frozen Elsa Cakes to Other Birthday Cakes

Standout Features and Visual Appeal

Frozen elsa cakes stand out thanks to their vibrant colors, edible snowflakes, and creative toppers. Compared to generic cakes, they offer a level of detail and visual impact that makes them memorable.

Guests are often impressed by the artistry, and the cake becomes a talking point throughout the event.

Versatility for Different Occasions

While most popular for birthdays, frozen elsa theme cakes are also perfect for winter parties, themed baby showers, and even holiday gatherings. Their versatility means you can adapt the design to suit any event, large or small.

Practical Considerations Before Buying

Price Range and Budgeting Tips

The cost of a frozen elsa theme cake varies depending on size, complexity, and location. Simple designs may start around $60, while elaborate multi-tiered cakes can exceed $200.

To stay within budget, consider opting for a smaller cake or supplementing with matching cupcakes and cookies. Discuss your preferences and budget with your baker to find the best solution.

Finding the Right Baker or Bakery

Choose a bakery with experience in themed cakes and positive reviews. Ask to see a portfolio of previous frozen elsa cakes and discuss your vision in detail.

Book early, especially for popular dates, as custom cakes often require advance notice.

Tips to Maximize the Value of Your Frozen Elsa Cake

Coordinating Party Decor and Activities

Enhance the impact of your frozen elsa cake by matching your party decor to the cake’s theme. Use blue and white decorations, snowflake banners, and Frozen-themed tableware for a cohesive look.

Plan activities like snowflake crafts or a “Let It Go” singalong to keep guests entertained and tie the celebration together.

Ensuring Dietary Needs Are Met

Many bakeries offer gluten-free, nut-free, or vegan options for frozen elsa cakes. Be sure to discuss any allergies or dietary restrictions with your baker in advance.

This ensures every guest can enjoy a slice without worry.

Frequently Asked Questions about Frozen Elsa Theme Cakes

How to Order and Customize

Start by researching local bakeries with experience in character cakes. Share your ideas, preferred flavors, and any special requests.

Most bakers require at least a week’s notice for custom designs, so plan ahead to secure your spot.

Best Occasions for an Elsa Cake

Frozen elsa cakes are ideal for birthdays, but they also shine at winter-themed events, baby showers, and family gatherings. Their universal appeal makes them a safe choice for any celebration where you want to create joy and excitement.

Conclusion

So, is a frozen elsa theme cake worth it? For many families and fans, the answer is a resounding yes. These cakes offer more than just a sweet treat—they create magical memories, delight guests, and serve as a stunning centerpiece for any event.

With endless design possibilities, emotional value, and the ability to bring the magic of Frozen to life, a frozen elsa theme cake is a worthwhile investment for anyone looking to make their celebration truly special.

From One Household to Another: Navigating the Intricacies of Foreign Domestic Worker Transfers

Hiring a foreign domestic worker (FDW) can be an essential move for Singaporean households that need assistance with daily chores, childcare, and elderly care. However, when transferring FDWs from one employer to another, the process can become more complex as these workers bring along expectations and experiences from their previous work environments. This article aims to help employers navigate this intricate situation by addressing some key aspects of the transfer process.


Communication is Key

One of the most important aspects of navigating the transfer process is establishing clear and open communication between the employer and the FDW. It is crucial to discuss expectations, job responsibilities, and any concerns that may arise during the initial stages of employment. By fostering a healthy dialogue, both parties can better understand each other’s needs and work towards a harmonious working relationship.


Be Open to Learning from Each Other

Employers should acknowledge that FDWs come with their own set of experiences and skills, which can be valuable for the household. Instead of dismissing their previous work practices, consider discussing what worked well for them and how it could potentially be incorporated into your household routine. This approach not only shows respect for the FDW’s expertise but also promotes a collaborative and flexible work environment.


Establish Clear Guidelines and Boundaries

While embracing new ideas and perspectives is essential, employers must also set distinct guidelines and boundaries for their FDWs to ensure a harmonious working relationship. This encompasses various aspects such as house rules, daily schedules, and specific job responsibilities, as well as outlining expectations for behavior, time management, and communication with the employer and other household members. By offering a transparent structure and unambiguous instructions, employers can facilitate a smoother transition for their FDWs into the new work environment. This approach minimizes the chances of misunderstandings or conflicts arising due to misaligned expectations between both parties. Additionally, it fosters an atmosphere of mutual respect, trust, and collaboration, enabling the FDW to feel more comfortable and empowered in their role. Ultimately, this contributes to a productive and positive working dynamic that benefits both the employer and the FDW.


Be Patient and Supportive

Transitioning to a new household can be challenging for FDWs, particularly when they bring expectations from their previous employers and need to adapt to different environmental factors. Changes in cultural norms and even family dynamics can significantly impact their performance and overall well-being. It is essential for employers to be patient and supportive during this period, allowing the worker ample time to adjust to the new environment and acclimate to these changes. Employers should offer guidance and encouragement when necessary, addressing any concerns or difficulties the FDW may face due to these environmental factors. Additionally, maintaining an open line of communication and providing constructive feedback on their performance will help create a collaborative atmosphere that fosters growth, understanding, and a strong working relationship between both parties. Ultimately, this empathetic approach will contribute to the FDW’s successful integration into the new household and positively impact their ability to perform their duties effectively.


Seek Professional Help When Necessary

In some cases, employers and FDWs may face difficulties in resolving conflicts or adapting to each other’s expectations. If such issues persist, consider seeking help from professional sources, such as employment agencies or support groups for FDWs. These organizations can provide valuable advice and resources to help both parties navigate the challenges they may face.


Final Thoughts

Navigating the intricacies of foreign domestic worker transfers can be a delicate process, requiring employers to balance their own expectations with those of their new FDW. By fostering open communication, establishing clear guidelines, and being patient and supportive, employers can help their FDWs transition smoothly into their new roles. In turn, this promotes a harmonious working relationship that benefits both the household and the FDW.

Scroll to top